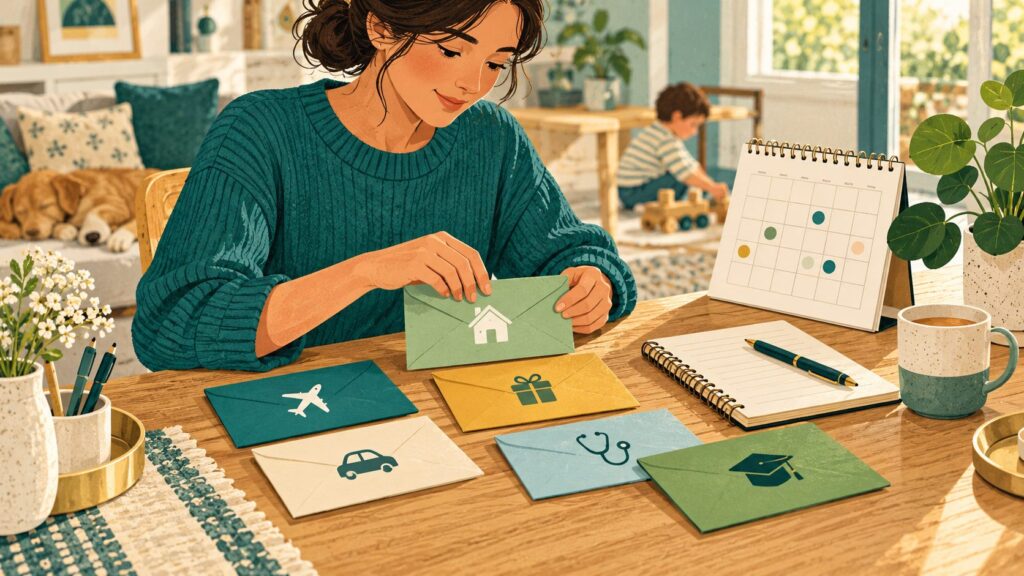
A sinking fund is a simple way to prepare for costs you can see coming, even when they do not arrive every month.
School shoes, annual insurance, car maintenance and seasonal celebrations can feel like sudden emergencies when the money has not been set aside. A sinking fund spreads an expected cost across the time before it is due. It is a planning method, not an extra bill to add when your budget has no room.
Sinking fund or emergency fund?
A sinking fund is for a known or likely cost: the car’s annual MOT, school uniform, a planned trip or a replacement appliance you know is nearing the end of its life. An emergency fund is for something unexpected. Keeping the ideas separate can make it clearer what money is already committed.
Choose only the costs that matter
Start with the irregular expenses that have caused the most stress or have a date attached. Check bank statements and last year’s bills for clues. Common categories include:
- school uniform, shoes and school activities
- car servicing, MOT, repairs and public transport changes
- annual insurance, licences or memberships
- birthdays and seasonal celebrations
- home maintenance and appliance replacement
- planned family trips or children’s activities
Do not make a separate pot for every possibility. Two or three clear priorities are easier to maintain than a complex system.
Work out a target that fits real life
Estimate the amount you want to have by the date you need it, subtract anything already saved for that purpose, then divide the remainder by the number of pay periods left. For example, a household choosing to spend £180 on a predictable annual cost, with 9 months to prepare and nothing already saved, would need to set aside £20 a month to reach that chosen target. This is an arithmetic example, not a suggested spending level.
If that amount is not affordable, lower the target, extend the time if possible, or record the shortfall and ask whether there is support. Do not put essentials or priority bills at risk to fill a savings pot.
Keep the money findable
Use labelled pots, a separate savings account or a simple spreadsheet—whichever you can check easily. Make sure you understand access times and any account terms before moving money. If your income varies, review the contribution each pay period instead of relying on an automatic transfer that may push the account into overdraft.
Use the fund when the cost arrives
When the bill is paid, update the balance and decide whether to restart the fund for the next cycle. If you use the money for something else, rename or recalculate the goal so you are not counting the same pounds twice.
If debts or missed essential bills are already a concern, get advice before prioritising savings. MoneyHelper’s bill prioritiser can help identify which payments need attention, and its debt advice locator finds free, confidential help. Build this method into your family budget, one affordable goal at a time.
A practical sinking-fund worksheet
Use one line per expense. Write the next date it is due, a sensible estimate, any amount already set aside and how many pay periods remain. The calculation is:
(chosen target − amount already saved) ÷ pay periods remaining = planned contribution per pay period.
For example, if you decide on a £150 target, have £30 already saved and have six months before the cost, the remaining £120 divided by six is £20 per month. This is an arithmetic illustration, not a recommended uniform or holiday budget. Use your own estimate and dates. If the result is unaffordable, lower the target, change what you plan to spend, seek a longer preparation period or mark the gap as something to discuss—do not treat the formula as an instruction to sacrifice essentials.
| Expense | When due | Target | Already set aside | Pay periods left | Next step |
|---|---|---|---|---|---|
| Example: annual renewal | Month/date | Estimate | Current balance | Count | Review quote |
| Example: school items | Before term | School list | Current balance | Count | Ask about second-hand options |
| Your priority | Write date | Your choice | Write amount | Count | Choose one action |
How to choose the target
Use evidence where you have it: last year’s invoice, a current quote, a school’s published list, a service schedule or a realistic replacement estimate. If the cost can change, record a range and note what would make it higher or lower. Do not use another family’s holiday, Christmas or car-repair spending as your target. The amount should reflect the choice your household intends to make.
For purchases you can control, set the budget first and compare the options afterward. For a required bill, confirm the amount and due date with the provider. It can be useful to create separate lines for costs that happen at different times, such as insurance and vehicle maintenance, because using one pot for both can cause a shortfall.
What if the expense is uncertain?
Some future costs are likely but the date or amount is unclear: an appliance nearing the end of its life, a car repair, a child’s next shoe size or home maintenance. Start with one priority and a broad estimate. Review it when you get a quote or new information. This is a planning reserve, not a promise that the exact cost is known.
For variable costs such as birthdays or seasonal spending, decide the total your household is comfortable with and list what it must cover. Do not quietly add every social invitation or school event to a fund without checking whether it is affordable. You can set limits, decline an expense or ask for more information.
Manage pots when money is tight
A separate bank account is optional. A note, spreadsheet or labelled pot inside an existing account may be enough. If using a financial product, check access, fees and terms. Keep a record of the balance allocated to each goal so the same amount is not promised twice. Be cautious with automatic transfers if pay dates or amounts change; a transfer that triggers an overdraft is not helping.
If you cannot contribute this month, update the expected balance and revisit the plan. That does not mean you have failed. You may decide to spend less on the event, use a suitable second-hand item, ask about payment dates, postpone a non-essential purchase or seek support. Keep essentials and current priority bills ahead of optional sinking funds.
When the bill arrives
Check the invoice or renewal against your estimate before paying. If the amount is much higher, ask why and compare alternatives only where switching is safe and allowed. Pay from the relevant fund, note the remaining balance, then restart the goal if the cost repeats. For a one-off expense, close the line so it does not keep appearing in your monthly plan.
If you used a fund for an emergency, record what happened and decide whether the fund needs a new purpose. Do not treat a planned car service or annual school expense as an emergency just because the fund is empty; the label should help the family distinguish foreseeable costs from surprises.
Coordinate sinking funds with debts and savings
Before setting aside money for optional future spending, make sure your current essentials and payments at risk are understood. If you have arrears, ask a free debt adviser which payments are most urgent. Do not assume that saving for a known cost always comes before a priority bill or that every debt must automatically be cleared before keeping any accessible cash; your circumstances matter. Get advice if the choice feels difficult.
Use our family budget guide to fit the figures into your monthly plan, and our emergency-fund guide to distinguish expected costs from surprises. The purpose of a sinking fund is to reduce future shocks where there is room to plan—not to add pressure where there is no spare income.
Choose a low-maintenance review rhythm
Once a month, check each active fund’s target, balance, next due date and whether the estimate still makes sense. Update it after a price quote, a school policy change, a car repair or a change in income. If the expense is no longer planned, close the pot and give the balance a new purpose rather than letting it disappear into an untracked account.
For school costs, start from the current school list and ask what is compulsory, what can be bought generically and whether a second-hand scheme exists. Requirements and rules vary by nation and school. In England, the Department for Education’s current cost of school uniforms guidance explains affordability and second-hand provision. Do not assume the same policy applies in every UK nation.
Decide what “ready” means
A fund does not always need to cover the entire ideal cost. For a predictable expense, decide what would make the next payment manageable: the full amount, the deposit, the first essential item or a share of the bill. If the target is not achievable by the due date, contact the provider or school early and ask what options exist. Do not assume a payment plan or grant is available; check the terms directly.
When comparing an annual payment with monthly instalments, compare the total cost, fees, cash flow and whether paying annually would leave too little for essentials. A lower total is not automatically the best choice if it creates a shortfall today.
A sinking fund should lower stress by making a future cost visible. If maintaining the system feels like another burden, simplify it: keep only the two most disruptive costs, use one note and review it on payday. A simple plan that is current is more useful than a detailed one no one can maintain.